Vendor evaluation is not seasonal. Contracts come up for renewal year-round, and a tool that is not earning its spot does not wait for a convenient month to become a problem. But budget season puts it in sharper focus than usual, since every vendor on the books gets a harder look right as 2027 technology budgets lock in.
On paper, the broader market looks like it is settling into that same calm. Apartment vacancy dropped below 9% for the first time since 2024, and national rents posted their first positive month in four years.
Underneath that stability, the industry is running its own version of the same exercise, just at a much bigger scale. REITs are merging into bigger platforms. Portfolios are trading hands at a faster pace than they were a year ago. And the vendors operators deal with every day are getting the same scrutiny that used to be reserved for acquisitions: the leasing platform, the maintenance software, the access control system, all of it.
Everyone is asking a version of the same question: are we running too many separate relationships to compete?
Here is a deeper look at five things every multifamily operator should understand about vendor consolidation heading into 2027.
1. The Industry’s Merger Wave Is a Preview of Your Own Vendor Audit
This year’s REIT activity is the clearest evidence that consolidation logic is winning. Centerspace and Independence Realty Trust merged into an $8.1 billion REIT spanning 44,354 units across 17 states, with roughly $24 million in projected synergies expected within 12 months of close. That followed the AvalonBay–Equity Residential merger that closed in August, rebranded as “Vivmark,” creating a platform with more than 184,000 units and roughly $70 billion in enterprise value.
Synergies at that scale rarely come from charging residents more. In most mergers, a meaningful share comes from cutting duplicate contracts: two accounting systems, two leasing platforms, two of everything, collapsed into one. That is the same math that plays out anytime a company decides two vendors are doing a job that one could handle.
Consolidation is not limited to headline mergers, either. Portfolio-level trading is up too: overall portfolio sales rose 21% year-over-year to $3.4 billion in July, with a single $1.6 billion California portfolio sale accounting for 40% of all mid- and high-rise trades that month. Some operators are getting bigger through merger while others are getting smaller and more focused by selling down. Both moves come from the same instinct: trim what does not need to be there.
The pattern, not any single deal’s price tag, is the useful takeaway. Nobody merges two companies planning to end up managing twice the vendors, and nobody sells off a portfolio planning to add complexity. Whether an operator is getting bigger or smaller, the direction of travel is the same: fewer, more deliberate relationships instead of a long list of point solutions.
What This Means for Your Vendor List:
Before your 2027 budget locks in, run the same exercise the REITs are running. List every vendor relationship you hold today and ask which ones would survive a merger, meaning which ones are doing distinct, necessary work, and which ones are quietly duplicating something you already pay for elsewhere.
2. The Real Vendor Audit: Evaluating What You’re Paying For
Research from NMHC and RETTC puts the average multifamily operator’s technology vendor count at 10 to 20 providers at any given time. This includes leasing, resident experience, access control, maintenance, and revenue management. That range is not the surprising part. The surprising part is how few operators can confidently say which of those tools are actually earning their spot.
Part of the problem is structural. The typical evaluation cycle leans heavily on vendor-supplied ROI numbers and hand-picked case studies, then repeats itself the same way when performance falls short. Underperforming tools stay in the stack because removing them feels riskier than tolerating them. New tools get layered on top instead of replacing what is not working, which is exactly how a portfolio ends up with 10 to 20 vendors in the first place.
A real audit does not start with a demo. It starts with the list you already have. For every vendor currently on your books, ask:
- What would actually break if we cancelled this tomorrow? If the honest answer is “not much,” it belongs on your cut list.
- Is this solving a problem another tool in our stack already solves, just less visibly?
- Are we evaluating this vendor’s performance against independent data, or against the case studies the vendor handed us?
- Who on our team owns this relationship, and would they notice if the tool quietly stopped delivering value?
Running through that list honestly, vendor by vendor, is a very different exercise than sitting through another demo and comparing feature checklists. It reframes the question from “what can this new tool do” to “what is our current stack actually doing for us,” which is the question that determines whether next year’s tech budget grows or shrinks.
What This Means for Your Vendor List:
Before adding another platform to your 2027 stack, audit the one you already have. A vendor list built from honest audits, not accumulated demos, is what separates operators who consolidate on purpose from operators who just keep adding.
3. Turnover Multiplies Every Fragmentation Problem You Have
A fragmented stack is only as reliable as the person who has memorized how to work around it. Having 10 to 20 vendors means 10 to 20 sets of logins, quirks, and workarounds, and most of that knowledge lives in one property manager’s head rather than anywhere written down. When that person leaves, the knowledge leaves with them.
That churn is constant. A recent NAA Survey found total turnover among onsite property-level employees reached 29.2% over twelve months, against 14.2% for corporate roles. Voluntary turnover alone hit 23.4%, up from 21.7% the year before. NAA’s own data shows 49% of operators managing 5,000 or more units name staffing as their single most persistent pain point, ahead of concessions, ahead of maintenance backlogs, ahead of almost everything else operators are asked about.
Every departure carries a direct cost, estimated at roughly $5,000 per replacement hire, before factoring in lost productivity. What that estimate does not capture is the relearning curve. A new hire walking into a 10-to-20-vendor stack is not just learning a community. They are relearning every login, every workaround, and every vendor relationship the last person built up over years, usually with no documentation to speed the process along.
Fewer vendors reduce contract count and the surface area that turnover has to hit. A property with three access-related systems and one leasing platform loses far less institutional knowledge with every departure than a property carrying ten disconnected tools, because there is simply less to relearn.
What This Means for Your Vendor List:
Factor retraining time into every renewal decision, not just the subscription fee. A vendor that is technically cheaper but takes a new hire three weeks to learn is not actually the cheaper option once turnover is priced in.
4. AI Is Entering the Stack Carefully & Scrutiny Is Right Behind It
Operators are taking a measured approach to AI rather than rushing it in, and that caution shows up clearly on the maintenance side of the business. Greystar, CAPREIT, and RPM Living all described AI as a multiplier for maintenance teams, not a replacement. Greystar’s managing director of maintenance said the technology is still mainly used to synthesize inspection data so teams can act faster, calling it “early stages.” RPM Living’s VP of facilities put it more bluntly: “AI is a great tool, but it’s not a replacement for a maintenance team member. At the end of the day, AI can’t complete repairs or turn an apartment.” CAPREIT’s technology chief added that ROI is still hard to prove because there is not enough data yet.
That caution is warranted well beyond maintenance. San Francisco’s ban on algorithmic rent-setting software is now two years old, and while enforcement has been thin, it produced the first lawsuit testing the ordinance this past July, filed by a tenant against a national management firm over its use of a rent-setting algorithm. Whatever the outcome, the case makes a point worth remembering: AI-driven pricing tools carry a kind of legal exposure that maintenance or leasing AI generally does not.
The distinction matters when you are the one deciding what to add to your stack. A maintenance AI vendor that overpromises might waste a subscription fee. A revenue management AI vendor that cannot clearly explain its data-sharing practices or fair housing safeguards can expose the operator, not just the vendor, to legal risk. Those are not the same conversation, and treating every AI vendor pitch the same way is how operators get caught off guard.
What This Means for Your Vendor List:
Ask maintenance and leasing AI vendors how they measure ROI before you buy. Ask revenue management AI vendors how they handle data-sharing practices, algorithmic transparency, and compliance safeguards before you buy those, too, and get the answer in writing.
5. One Platform, Not Five Logins: Why We Built Luxer Access
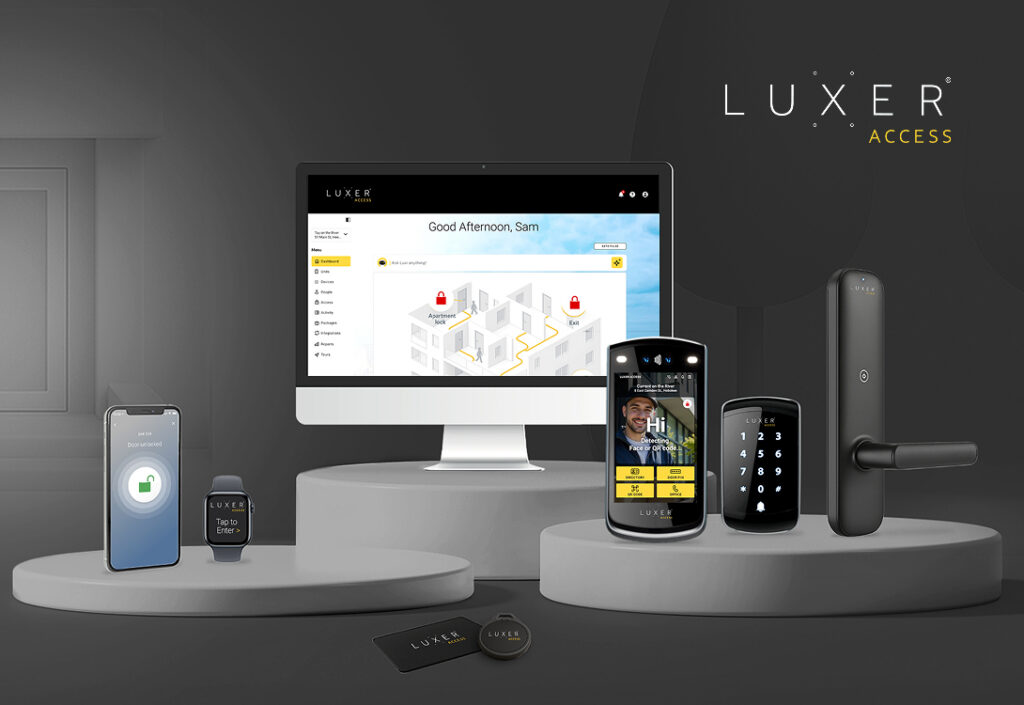
Access control is one of the most fragmented corners of the average tech stack. Video intercom, smart locks, delivery access, parking, and self-guided tours typically run on five separate systems, each with its own vendor, its own login, and its own support line. When something breaks, staff have to first figure out which vendor is responsible before they can even start troubleshooting.
Luxer Access was built to close that gap: all five categories under one platform, with one support team handling the whole relationship instead of five separate ones.
The payoff from this complete end-to-end ecosystem shows up most in the same situations we’ve covered in this piece. When a vendor gets cut during a budget review, when a staff member turns over, or when a new hire needs to get up to speed fast, fewer systems means fewer things to relearn and fewer handoffs to get wrong. Consolidating access control does not just simplify a line item on a vendor list, but removes an entire category of the relearning curve.
What This Means for Your Vendor List:
When you are auditing your stack this quarter, look at access control first. It is usually the category with the most vendors doing the least talking to each other, and the category where consolidation pays off fastest.
The Bottom Line for Budget Season
The industry is consolidating at every level right now, from REIT balance sheets down to individual property tech stacks. The operators who come out ahead this budget cycle will not be the ones who cut vendors for the sake of a smaller number. They will be the ones who audited their stack honestly, factored turnover and retraining into every renewal decision, and asked harder questions of every AI vendor pitching them something new.
Budget season just forces the question sooner. The audit itself is worth running any time of year. The data is available, the fatigue is real, and the direction the entire industry is moving in is clear. The only variable is whether your vendor list moves with it.
Download the Vendor Evaluation Checklist
Want a simple way to run this audit yourself? Download our Vendor Evaluation Checklist for Multifamily Operators, a one-time stack inventory plus a per-vendor worksheet covering the consolidation test, red flags to rule out, and what to ask before you sign or renew.
Join The Multifamily Brief Insider List for More
Already on the list? Check your email for this month’s resources!
-
See Posts
Christina Draper, Marketing Content Manager at Luxer One, creates storytelling-driven content that connects with property management professionals and highlights innovations in multifamily package management. With a marketing background from UNC Charlotte, she develops cross-channel campaigns that showcase how Luxer One is redefining the resident experience.